Recovery Math: Why a 10% Loss Needs More Than a 10% Gain to Break Even
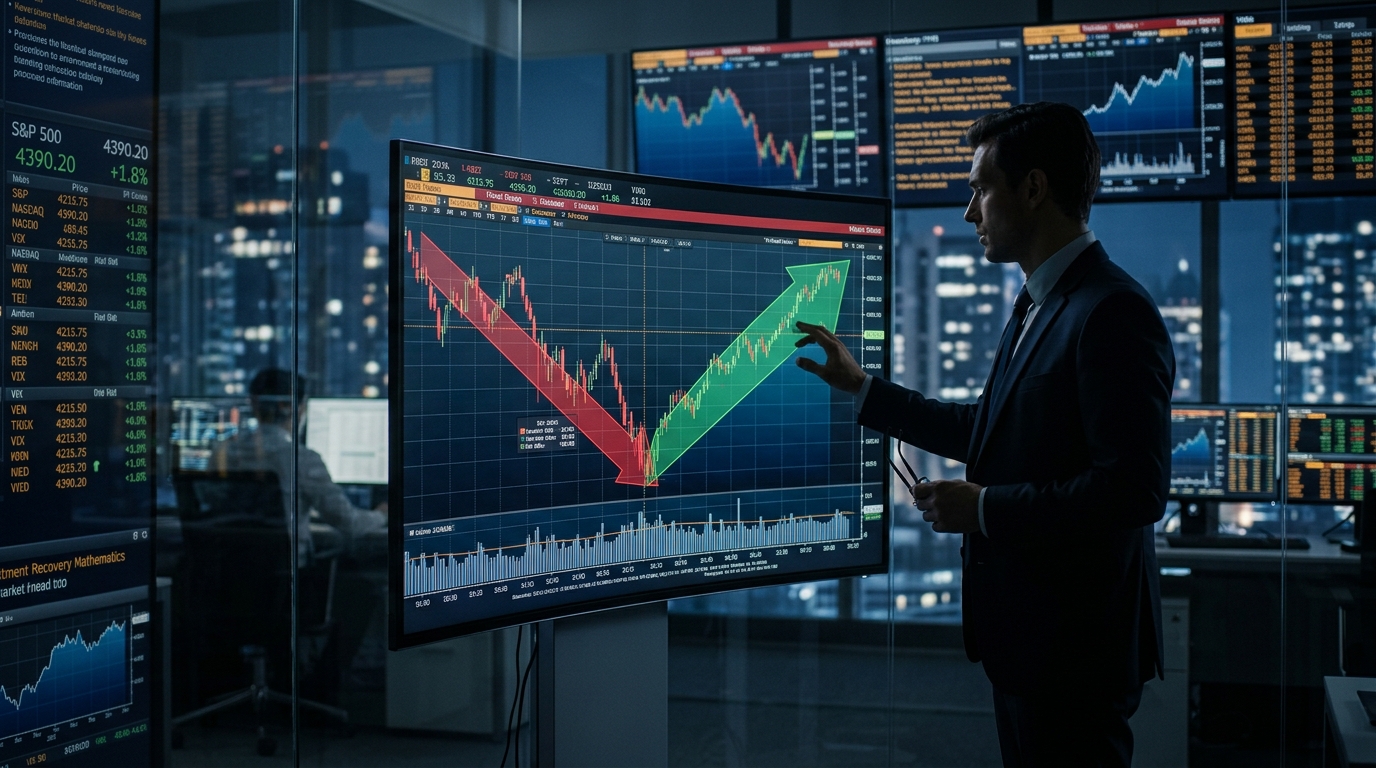
A 10% investment loss might seem easy to recover. After all, a 10% gain sounds like the perfect solution. However, investment recovery math tells a different story. A portfolio needs a gain above 10% to return to its original value.
This mathematical reality affects stock investors, retirement savers, and long-term traders. Moreover, larger losses create increasingly difficult recovery challenges. Understanding this relationship can help investors manage risk more effectively.
Why a 10% Investment Loss Requires an 11.11% Gain
Percentage losses and gains work differently because they use different starting values.
Consider an investment worth $10,000. A 10% decline reduces its value by $1,000. Consequently, the remaining investment balance becomes $9,000.
Now, calculate a 10% gain on that reduced balance. The investment increases by just $900. Therefore, its new value reaches $9,900.
The investor still needs another $100 to recover the original amount.
Instead, the investment needs an 11.11% gain on $9,000. That increase restores the portfolio to $10,000.
This difference explains why recovery percentages are not symmetrical.
How Investment Losses Change Recovery Requirements
The deeper an investment falls, the harder recovery becomes. Each additional percentage point creates a larger mathematical challenge.
Here are some examples using an initial investment of $10,000:
| Investment Loss | Remaining Value | Required Recovery Gain |
| 5% | $9,500 | 5.26% |
| 10% | $9,000 | 11.11% |
| 20% | $8,000 | 25% |
| 30% | $7,000 | 42.86% |
| 40% | $6,000 | 66.67% |
| 50% | $5,000 | 100% |
| 60% | $4,000 | 150% |
| 70% | $3,000 | 233.33% |
These numbers highlight an important investment principle. A 50% loss requires a 100% gain just to break even.
Similarly, a 70% decline requires more than tripling the remaining investment value. Therefore, protecting capital becomes increasingly important during market downturns.
The Mathematics Behind Investment Recovery
Investors can calculate the required recovery percentage using a simple formula:
Required Recovery Gain = (Loss Percentage ÷ (100 − Loss Percentage)) × 100
For example, assume an investment loses 20%.
The calculation becomes:
20 ÷ (100 − 20) × 100 = 25%
Therefore, the investment needs a 25% gain to recover its original value.
This formula works for any percentage loss below 100%. It also demonstrates why percentage declines and increases create different financial outcomes.
Why Market Volatility Makes Recovery More Difficult
Market volatility can make investment recovery even more challenging. Stock prices tend to fluctuate, with gains often interrupted by occasional dips and setbacks.
Instead, markets experience corrections, rallies, and sudden reversals. Consequently, investors may experience several gains and losses before recovering their original capital.
For example, imagine a stock declines 20% during a market correction. It then gains 10% during a short rally.
However, the stock remains below its original price. The initial decline reduced its value more than the subsequent rally restored.
Additionally, emotional decisions can make recovery harder. Some investors sell during market panic and miss subsequent rebounds.
Others take excessive risks because they want to recover losses quickly. Unfortunately, these decisions can increase financial damage.
How Investors Can Protect Their Portfolios
Investors cannot eliminate market risk completely. Nevertheless, several practical strategies can help limit unnecessary losses.
1. Set Clear Risk Limits
Decide how much portfolio risk you can reasonably accept. Establish investment rules before market conditions become stressful.
Moreover, review individual positions regularly. Avoid allowing one investment to dominate your overall portfolio.
2. Diversify Across Different Assets
Diversification spreads investments across different companies, industries, and asset classes.
As a result, weakness in one market segment may have less impact on the entire portfolio.
However, diversification does not guarantee profits or prevent losses. It simply helps manage concentration risk.
3. Avoid Emotional Investment Decisions
Market declines often create fear and uncertainty. Therefore, investors should avoid making rushed decisions based on short-term price movements.
Instead, review investment fundamentals and long-term financial goals. Also, distinguish temporary market weakness from permanent business deterioration.
4. Use Position Sizing Carefully
Position sizing determines how much capital goes into each investment.
Smaller positions can limit the damage caused by an unsuccessful trade. Furthermore, sensible allocation prevents individual mistakes from destroying an entire portfolio.
5. Maintain a Long-Term Perspective
Long-term investors should focus on portfolio quality and sustainable financial goals.
However, patience does not mean ignoring serious investment problems. Review your holdings and adjust allocations when circumstances change.
Why Preventing Losses Matters More Than Chasing Gains
Many investors spend considerable time searching for stocks with impressive growth potential. However, protecting existing capital deserves equal attention.
A portfolio that loses 10% needs an 11.11% recovery. Meanwhile, avoiding that initial decline preserves the original investment value.
This difference becomes even more significant during severe market downturns.
Furthermore, investors who control downside risk may have more flexibility during future market opportunities. They can allocate capital without first overcoming substantial losses.
Therefore, successful investing requires more than identifying winning stocks. It also requires understanding how losses affect future returns.
Conclusion: Understand Recovery Math Before Investing
Investment recovery math reveals an important financial truth. A percentage loss requires a larger percentage gain to restore the original balance.
A 10% decline needs an 11.11% increase. Meanwhile, a 50% decline requires a 100% gain.
These figures explain why risk management matters throughout every market cycle. Investors should prioritize sensible diversification, disciplined position sizing, and realistic expectations.
Ultimately, protecting capital can make long-term investment growth more achievable.