Small Business Bookkeeping: A Guide to Staying Organized Without an Accountant
Many small business owners put off bookkeeping until tax season forces the issue, then spend a frantic week reconstructing a year of transactions from bank statements and memory.
That approach works, barely, but it hides small problems that a current set of books would have caught months earlier, from a client who quietly stopped paying to a subscription nobody remembers ever signing up for.
Staying organized year-round does not require a professional accountant on staff. It requires a handful of habits, a simple system, and enough consistency to keep the numbers trustworthy at any point in the year, not just in April.
The cost of neglecting this task rarely shows up immediately, which is part of why it is so easy to postpone. A missed subscription cancellation or an unnoticed billing error might only cost a modest amount each month, but left unchecked for a year or two, those small leaks add up to a surprising sum.
Clean, current books turn invisible problems like these into something that gets noticed within a week or two rather than quietly draining the business for a long stretch of time.
Separating Business and Personal Finances First
Every bookkeeping guide starts here for a reason: mixing business and personal transactions in a single account creates a mess that compounds every month it continues.
A business owner who pays for client dinners, software subscriptions, and personal groceries out of the same account has no simple way to know what the business truly spent without manually sorting through every single line item later.
- Open a dedicated business bank account: Even a sole proprietor with no legal requirement to separate accounts benefits a great deal from doing so anyway.
- Get a business credit card: Routing business expenses through a dedicated card creates a clean, automatic record separate from personal spending.
- Pay yourself a set amount, not as-needed: Transferring a consistent amount from the business account to a personal account, rather than pulling money whenever needed, keeps the business’s real cash position visible.
- Avoid loaning money between accounts casually: If a personal fund truly needs to cover a business expense, record it formally rather than letting the transfer blur the line between the two.
This separation alone resolves a large share of the confusion that drives small business owners to put off bookkeeping altogether, since it removes the need to mentally sort every transaction after the fact.
Picking a Bookkeeping Method That Fits the Business
Not every small business needs the same level of bookkeeping complexity, and picking a method that matches the size and nature of the business avoids both the frustration of an overly simple system that cannot keep up and the wasted effort of an overly complex one.
- Cash-basis accounting: Records income and expenses when money changes hands directly, which is simpler to maintain and fits most very small service businesses well.
- Accrual-basis accounting: Records income and expenses when they are earned or incurred, regardless of when cash moves, which better suits businesses with inventory or sizable receivables.
- Spreadsheet-based tracking: Works for a very small operation with few transactions, though it requires discipline to keep current and offers little automation.
- Dedicated bookkeeping software: Automates bank syncing, categorization, and reporting, which becomes worth the monthly cost once transaction volume grows past what a spreadsheet can comfortably handle.
Most businesses eventually land on cash-basis accounting paired with dedicated software, since it balances simplicity with enough structure to produce reliable reports without a steep learning curve.
Recording Transactions on a Regular Schedule
The single biggest predictor of whether a small business’s books stay accurate is how often transactions get recorded, not how sophisticated the system is. A business that reconciles weekly almost always has cleaner records than one using advanced software but updating it only once a quarter.
- Reconcile bank accounts weekly: A short weekly session catching errors, duplicate charges, or missing transactions prevents a backlog that becomes overwhelming by month’s end.
- Categorize expenses as they occur: Most bookkeeping software suggests a category automatically, and confirming it immediately is faster than guessing weeks later what an unlabeled charge was for.
- Save receipts immediately, not at month’s end: A photo taken on a phone right after a purchase is far more reliable than trying to reconstruct a receipt trail from memory later.
- Set a fixed day and time for bookkeeping: Treating it as a recurring calendar appointment, rather than something fit in whenever there is spare time, is what truly keeps the habit consistent.
A business owner who blocks even thirty minutes a week for this task rarely falls behind, while one who waits for a free afternoon often finds that afternoon never arrives.
Tracking Income and Expenses by Category
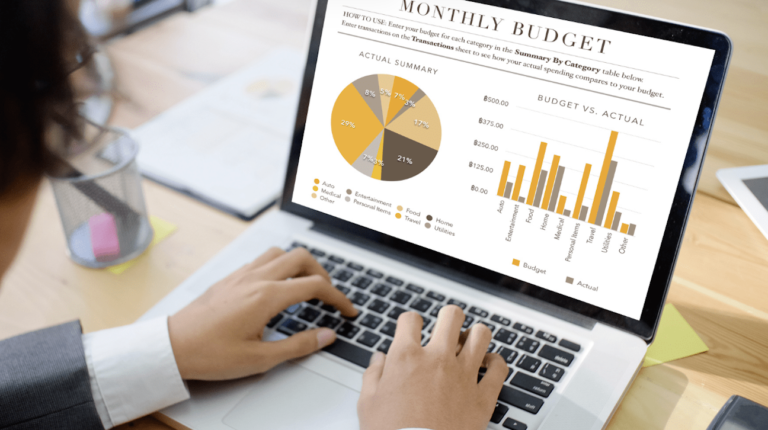
Beyond simply recording that money came in or went out, organizing transactions into clear categories turns raw numbers into information that can truly guide decisions. A business that only knows its total revenue and total expenses, without a breakdown, cannot tell which services are profitable or which costs are growing faster than they should.
- Separate revenue by product or service line: This reveals which parts of the business are truly driving growth and which may be worth reconsidering.
- Track recurring expenses separately from one-time costs: Subscriptions and recurring fees quietly accumulate over time and deserve a periodic audit of their own.
- Monitor cost of goods sold distinctly from overhead: For a product-based business, confusing these two categories makes it nearly impossible to calculate real profit margin with any precision.
- Flag unusual or large transactions for review: A large, unexpected expense should trigger a closer look rather than being filed away without a second thought.
Reviewing these categories monthly, rather than only at tax time, surfaces trends early enough to act on them while there is still time to make a real adjustment.
Reviewing Financial Statements Monthly
A handful of basic financial statements, reviewed consistently, give a small business owner a far clearer picture of their company’s health than a bank account balance ever could on its own. The balance in an account reflects a single moment, while financial statements reveal patterns and trends over time.
- Profit and loss statement: Shows total revenue, expenses, and net profit over a chosen period, making it the fastest way to spot a declining trend before it becomes a crisis.
- Balance sheet: Lists assets, liabilities, and equity at a given point in time, offering a snapshot of overall financial position beyond just monthly cash flow.
- Cash flow statement: Tracks the real movement of cash in and out, which matters because a profitable business can still run short on cash if payments are delayed.
- Accounts receivable aging report: Flags unpaid client invoices by how overdue they are, which is often the earliest warning sign of a cash flow problem forming.
Most bookkeeping software generates these reports automatically once transactions are categorized correctly, turning what used to require a dedicated accountant into a few clicks reviewed over coffee once a month.
Pairing this monthly review with a short list of a handful of key numbers, rather than trying to absorb every line of every report, makes the habit sustainable over the long run. A busy owner who commits to checking net profit, total cash on hand, and the balance of overdue client invoices each month will catch the vast majority of problems worth catching, even without reading every report cover to cover.
Adding a brief written note after each review, just a sentence or two about anything that stood out, builds a simple record of the business’s financial story over time that is far more useful than memory alone when looking back a year later to see how the business has changed.
Preparing for Tax Season Throughout the Year
Tax preparation becomes dramatically easier when it is treated as a year-round habit rather than a single frantic event each spring. A business that keeps clean, categorized records throughout the year hands its accountant, or a tax software program, a nearly finished product instead of a shoebox of receipts to sort through under deadline pressure.
- Set aside a tax reserve regularly: Moving a percentage of each payment received into a separate savings account prevents a painful scramble when a tax bill arrives.
- Track deductible expenses as they happen: Mileage, home office costs, and professional development expenses are easy to miss if not logged consistently throughout the year.
- Keep digital copies of every receipt: Cloud storage or dedicated receipt-scanning apps protect against a faded paper receipt becoming unreadable months later.
- Review estimated tax payments quarterly: Adjusting these payments as income changes avoids both an underpayment penalty and an unnecessarily large refund that could have been working capital instead.
Bookkeeping done well throughout the year essentially pre-writes most of the tax return before tax season even begins, leaving only the final filing steps for a professional or a software program to complete.
The emotional benefit of this approach matters just as much as the practical one. Owners who keep current books tend to approach tax season with a sense of routine rather than dread, since there are no surprises left to uncover and no missing documentation to chase down at the last minute. That shift in experience alone is often enough motivation to maintain the habit even during busy stretches of the year when bookkeeping feels like the easiest task to skip entirely.
Building a Simple Chart of Accounts
A chart of accounts is the complete list of categories a business uses to sort every transaction, and getting this structure right early on saves a tremendous amount of confusion later, since reorganizing years of historical transactions after the fact is a tedious and error-prone process that few owners want to repeat.
Most bookkeeping software comes with a default chart of accounts built for a generic business, but customizing it slightly to match the specific operation tends to produce far more useful reports down the line.
A chart of accounts that is too broad hides useful detail, while one that is too granular becomes a chore to maintain and ends up with categories so narrow that almost nothing gets filed under them consistently. A reasonable middle ground groups expenses into recognizable categories such as software, marketing, travel, supplies, and professional services, with just enough subcategories to separate anything the business specifically wants to track closely, such as advertising spend broken out by platform.
Revisiting the chart of accounts once a year, trimming categories that never get used and adding ones that have become relevant, keeps the structure matched to how the business has truly grown rather than how it looked when the books were first set up.
Handling Payroll and Contractor Payments Correctly
Payroll introduces a layer of complexity that trips up many small business owners who have otherwise kept clean books, since it involves tax withholding, filing deadlines, and legal classification questions that carry real penalties if handled incorrectly. Even a business with a single part-time employee needs to treat payroll as its own distinct process rather than folding it into general expense tracking.
The distinction between an employee and an independent contractor matters more than many new business owners realize, since misclassifying a worker can trigger back taxes and penalties well after the fact.
Employees generally require withholding for income and payroll taxes, along with proper documentation, while contractors are typically paid a gross amount and handle their own tax obligations separately. Dedicated payroll software, even a low-cost option built for very small teams, handles the calculations, filings, and recordkeeping far more reliably than a manual spreadsheet approach, and the cost is usually modest compared to the risk of a compliance mistake discovered during an audit years later.
Final Thoughts
Staying organized without a full-time accountant comes down to consistency far more than complexity. Separating business and personal finances, recording transactions on a regular schedule, and reviewing a few key reports each month turn bookkeeping from a dreaded annual scramble into a routine part of running the business.
The owners who struggle most with their books are rarely the ones facing the most complicated finances; they are usually the ones who let a simple task pile up until it feels impossible to start.
Building the habit in small, regular sessions rather than waiting for a dedicated block of free time is what ultimately makes the difference between books that stay current and ones that quietly fall behind for months at a stretch.
Frequently Asked Questions
1. At what point does a small business need to hire a bookkeeper or accountant?
Many solo businesses and very small teams handle their own books successfully using dedicated software, but the calculation shifts once transaction volume, payroll, or inventory complexity grows past what the owner can manage alongside running the business itself. A common signal is spending more hours each month on bookkeeping than the cost of hiring part-time help would justify, or noticing that errors are creeping into the records because there simply is not enough time to review them carefully each week. Many businesses find a middle path works well: handling day-to-day entry internally while bringing in outside help for a periodic review, tax preparation, or more complex filings that carry real financial consequence if handled incorrectly.
2. How long should financial records be kept?
A common guideline is at least three to seven years, depending on the type of record and the specific local tax regulations that apply, since audits can sometimes reach back several years. Digital storage makes this far less burdensome than it once was, since scanned receipts and exported reports take up negligible physical space compared to the paper files of years past.
3. Is free bookkeeping software good enough for a small business?
Free tools can work for a very early-stage business with minimal transaction volume, but most growing businesses eventually need features like automatic bank syncing, multiple user access, or advanced reporting that free tiers typically do not include at all. Moving to a paid plan sooner rather than later often saves far more time than it costs once a business crosses a modest transaction threshold each month.
4. What is the difference between bookkeeping and accounting?
Bookkeeping is the ongoing process of recording and categorizing daily transactions, while accounting involves interpreting those same records to produce financial statements, tax filings, and strategic advice. A small business can often handle bookkeeping internally on a routine basis while still working with an accountant periodically for tax filing and bigger financial decisions that fall outside day-to-day record keeping.
5. How often should a small business reconcile its bank accounts?
Weekly reconciliation is ideal for most small businesses, since it catches errors or fraud quickly and prevents a large backlog of unrecorded transactions from building up. Monthly reconciliation is the minimum workable frequency, but waiting any longer than that makes it far harder to remember the context behind unusual or unclear transactions, and small discrepancies tend to multiply the longer they sit unresolved in the records.
6. Can bookkeeping software replace an accountant entirely?
Software handles the mechanical work of recording and categorizing transactions well, but it does not replace the judgment an accountant brings to tax strategy, complex filings, or financial planning decisions. Most small businesses get the best results from a combination: software for daily bookkeeping and periodic professional guidance for the decisions that carry real financial consequence, such as structuring a major purchase, planning around a large tax bill, or deciding how to handle a change in the business’s legal structure. Treating software and professional advice as complementary tools, rather than choosing one over the other entirely, tends to serve a growing business better than relying exclusively on either approach alone.