Why Wells Fargo Saw 31% Sales Increase With AI
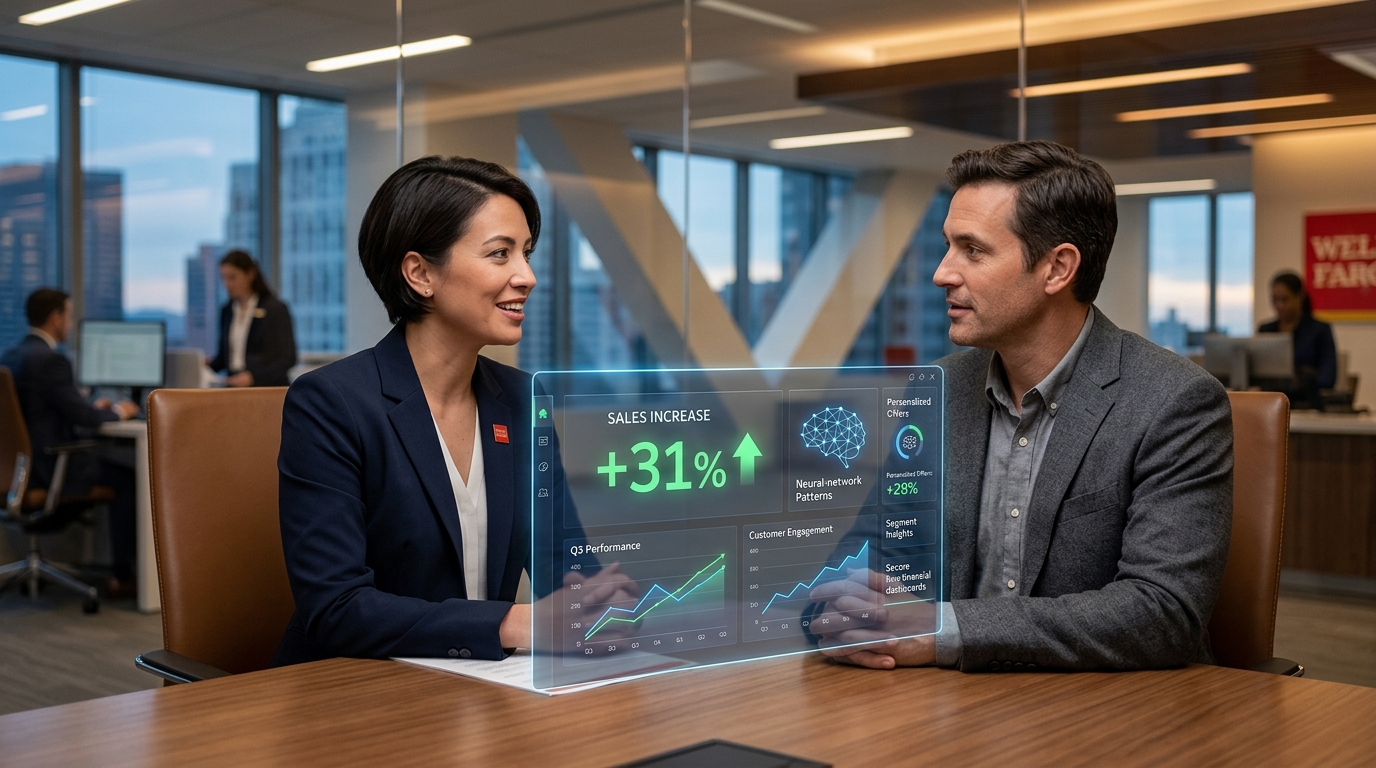
A 31% increase in sales is a striking result for a bank, but the more interesting detail is what happened behind the number: Wells Fargo found that AI could help bankers sell more effectively without simply replacing them.
The story matters beyond banking. If AI can help financial professionals identify opportunities, prepare for customer conversations, and act on useful information faster, the same model could change sales teams across many industries.
The key lesson is not that AI magically creates revenue. It is that AI works differently when it supports people at the exact moment they need help.
The Wells Fargo AI Sales Increase Was Really About Human Behavior
The surprising part of the Wells Fargo AI story is that the technology itself was not the entire reason for better sales performance.
AI can analyze information quickly, but a banker still has to understand a customer, build trust, explain products, and make a recommendation. The technology becomes useful when it reduces the time spent searching for information and increases the time available for meaningful customer interactions.
That changes the role of the banker.
Rather than focusing on what to sell, a banker can use relevant cues to identify services that may suit a customer’s needs.
The difference sounds small. In practice, it can change the entire sales conversation.
Wells Fargo has publicly discussed its use of AI and machine learning to improve employee and customer experiences. Its AI work includes tools designed to help employees find information and make better decisions.
What nobody tells you about AI-powered sales
The strongest AI sales systems do not simply generate more messages or advertisements.
They improve the timing and relevance of human action.
Imagine a banker handling dozens of customer interactions. Without AI, identifying the right opportunity may require checking multiple systems, reviewing account information, and remembering product rules.
With an AI-supported workflow, useful information can appear at the right point in the process.
That saves time.
And saved time can become customer conversations, follow-ups, and completed sales.
The Real Reason Wells Fargo AI Could Increase Sales
The real reason behind the Wells Fargo AI sales increase is easier to understand when you stop thinking about AI as a salesperson.
Think of it as a decision-support system.
A good system can surface patterns that humans might miss. It can help employees prioritize customers, locate information, summarize complex material, or identify possible next steps.
This matters because sales performance is often limited by friction.
A banker may know that a customer could benefit from another financial service, but finding the relevant information can take time. The customer may leave before the conversation develops.
AI can reduce that friction.
The result is not necessarily a dramatic change in what employees do. Instead, it can make existing work faster and more targeted.
That distinction is critical for businesses considering AI investments.
Buying an AI tool is easy. Redesigning a workflow around that tool is much harder.
AI does not replace the relationship
Banking is built around trust. Customers often want explanations, reassurance, and context before making financial decisions.
That is difficult to automate completely.
AI can suggest an opportunity, but a human can decide whether bringing it up makes sense. A banker can also understand tone, hesitation, family circumstances, business concerns, or questions that may not appear in structured data.
This human-AI combination may explain why AI-assisted sales can perform differently from fully automated sales.
The machine handles information.
The person handles the relationship.
And that matters because financial products can have serious consequences for customers.
Did You Know?
AI in banking is increasingly being used for more than chatbots. Banks apply machine learning and generative AI to employee assistance, customer service, fraud detection, document processing, risk analysis, and personalized experiences. The biggest gains often come when AI is embedded inside an existing workflow rather than offered as a separate tool.
Most People Think AI Sales Means Automation, But It Often Means Assistance
One of the biggest misconceptions about AI is that companies need to automate an entire job before they can see meaningful benefits.
The Wells Fargo example points toward a different model.
AI can improve a job without taking the job away.
For a banker, that could mean summarizing information before a meeting. It could mean helping answer an internal question. It could identify a possible customer need or make relevant information easier to find.
These small improvements can compound.
Suppose a banker saves several minutes during every customer interaction. Over dozens of conversations, those minutes become hours.
Those hours can be redirected toward customers.
That is where the financial value can emerge.
Why small improvements can become large revenue changes
Sales organizations rarely depend on one giant action.
They depend on hundreds of small decisions.
Who should receive a follow-up? Which customer needs attention? What information should be presented? Which product is relevant? When should the employee contact the customer?
AI can influence many of those decisions.
Even a modest improvement at each stage can affect the final result.
This is also why businesses should be careful when interpreting a 31% figure. A sales increase associated with AI does not mean AI alone caused every dollar of additional revenue. Business performance can be affected by market conditions, employee training, product changes, customer demand, and many other factors.
The number is interesting, but the mechanism behind it is even more useful.
The Hidden Advantage Is Giving Bankers Better Information
Here is the part many AI discussions miss: information has value only when people can act on it.
A bank may have enormous amounts of customer data. That does not automatically make employees more productive.
The challenge is turning data into useful information at the right moment.
AI can help with that conversion.
A banker does not necessarily need to see every piece of information available. They need the information relevant to the conversation happening right now.
This is where AI assistants, recommendation systems, search tools, and generative AI can become powerful.
Instead of forcing employees to search through large databases, the system can help bring the right information forward.
In my experience with clients, I have noticed that AI projects become more useful when the technology is connected to a specific business problem rather than introduced simply because AI is popular.
The same principle applies to banking.
The customer may benefit too
Better employee tools can improve customer experiences when they reduce waiting, confusion, or unnecessary transfers.
A banker who can quickly locate an answer may resolve a question during the same interaction.
A banker who understands a customer’s situation more clearly may provide a more relevant explanation.
That can create value on both sides of the counter.
But there is another side.
Banks must manage privacy, security, model accuracy, regulatory requirements, and the risk of inappropriate recommendations. Financial services cannot treat AI like a simple productivity app.
Human oversight remains important.
Wells Fargo’s AI Story Shows Why Implementation Matters More Than Hype
The biggest lesson from the Wells Fargo AI sales increase is not “AI makes sales go up.”
The more useful lesson is this:
AI creates business value when it is connected to a measurable workflow and people know how to use its output.
A company could spend millions on AI and see little return if employees do not trust the system or if its recommendations arrive too late.
Another company could start with a smaller tool that removes a major bottleneck and see a meaningful operational improvement.
That is why implementation matters.
Companies should identify the task first.
Then they should determine whether AI can improve it.
They should measure the result.
And they should keep humans involved where judgment, accountability, and customer trust matter.
Three questions businesses should ask before copying the model
First, what decision is taking employees too long?
Second, what information could AI organize or surface faster?
Third, how will the company measure whether the change actually improves results?
These questions are more useful than simply asking which AI platform a company should buy.
Did You Know?
A useful AI business metric does not have to be “number of AI users.” Companies can measure time saved, conversion rates, response times, error rates, customer satisfaction, employee adoption, and revenue associated with specific workflows. Those measures make it easier to separate real business value from AI hype.
The Future of AI Banking May Look More Human, Not Less
The Wells Fargo AI sales increase points toward a future where AI becomes part of everyday employee work rather than a separate destination.
A banker may not think about “using AI” every time the technology helps.
It may simply appear as better search, smarter recommendations, automatic summaries, faster document analysis, or a more useful customer profile.
That could be the most important shift.
The future of AI in banking may not be about removing humans from customer relationships. It may be about giving humans better tools for those relationships.
The same idea applies to insurance, retail, healthcare administration, real estate, and professional services.
AI can handle more of the information burden.
People can spend more time making decisions and communicating with customers.
The bottom line is simple: the Wells Fargo example shows why companies should look beyond flashy AI demonstrations. The strongest business results may come from quiet improvements inside everyday workflows.
What would you want AI to handle if it could remove one frustrating task from your workday?
Frequently Asked Questions
What caused Wells Fargo’s AI-related sales increase?
The reported increase is associated with AI-supported banker workflows that can help employees identify opportunities and work with customer information more efficiently. AI should not be treated as the sole cause of revenue changes because sales can also be affected by market conditions, employee behavior, products, and broader business factors.
How does Wells Fargo use AI?
Wells Fargo has used AI and machine learning across areas including employee assistance, customer experiences, fraud detection, and other banking processes. Specific tools and applications can change over time. The broader strategy is to use AI to help employees and systems process information, identify patterns, and support faster decisions.
Can AI replace bank employees?
AI can automate some tasks, but replacing entire banking roles is a different question. Banking involves judgment, communication, compliance, and customer trust. AI can support employees by handling information-heavy work while people remain responsible for decisions and customer interactions, especially where financial consequences or sensitive information are involved.
Is a 31% sales increase guaranteed with AI?
No. A reported sales increase from an AI-supported program should not be treated as a guaranteed result for other companies. Outcomes depend on implementation, employee adoption, customer behavior, data quality, product fit, measurement methods, and market conditions. Businesses should test AI against specific performance metrics before expanding it.