Business Credit Cards: A Guide to Separating Personal and Company Spending
Running a business through a personal credit card might feel harmless in the early days, especially for a solo founder paying for a handful of modest expenses each month. That habit quickly becomes a liability as the business grows, tangling personal and company finances in a way that complicates taxes, obscures true profitability, and can even expose personal assets to unnecessary business risk.
A dedicated business credit card draws a clean, lasting line between the two, and the benefits extend well beyond simple bookkeeping convenience alone.
The decision to separate these finances often gets postponed simply because the business feels too small to justify the paperwork involved in applying for a dedicated card.
In practice, the application process for most business cards takes only a few minutes longer than a typical personal card application, and the benefits of making the switch early, well before years of mixed transactions accumulate, far outweigh that small upfront time cost. Waiting until the business has grown much larger only makes the eventual cleanup harder, since there is simply more history to untangle by that point.
Clarifying Why Mixing Finances Creates Real Risk
Beyond the obvious bookkeeping headache, mixing personal and business spending on one card carries consequences that many owners underestimate until they encounter them directly. The risks touch legal protection, tax compliance, and the accuracy of the financial picture a business owner relies on to make decisions.
- Weakened liability protection: For a business structured as a limited liability company or a corporation, commingling personal and business funds can slowly undermine the legal separation that protects personal assets from business debts.
- Harder tax preparation: Sorting personal purchases out of a mixed account at tax time is tedious and increases the risk of either missing a deductible expense entirely or incorrectly claiming a personal one as a business cost.
- Distorted profitability numbers: A business owner cannot accurately judge how the company is really performing when personal expenses are blended into the same spending records.
- Increased audit risk: Mixed accounts draw far more scrutiny during a tax audit, since an auditor cannot easily verify which charges truly relate to the business and which do not.
Separating spending from the earliest days of a business, even before it feels necessary, avoids a much more complicated cleanup process later once years of mixed transactions have accumulated.
Accountants and bookkeepers frequently cite this exact issue as one of the most common and most avoidable problems they encounter with small business clients. A business owner who waits until tax season to sort out a year of commingled charges often ends up paying for extra hours of professional time just to untangle what a dedicated card would have kept separate automatically from the start.
That added cost alone, in many cases, far exceeds whatever minor convenience was originally gained by skipping the setup of a dedicated business card in the first place.
Comparing Card Types for Different Business Needs
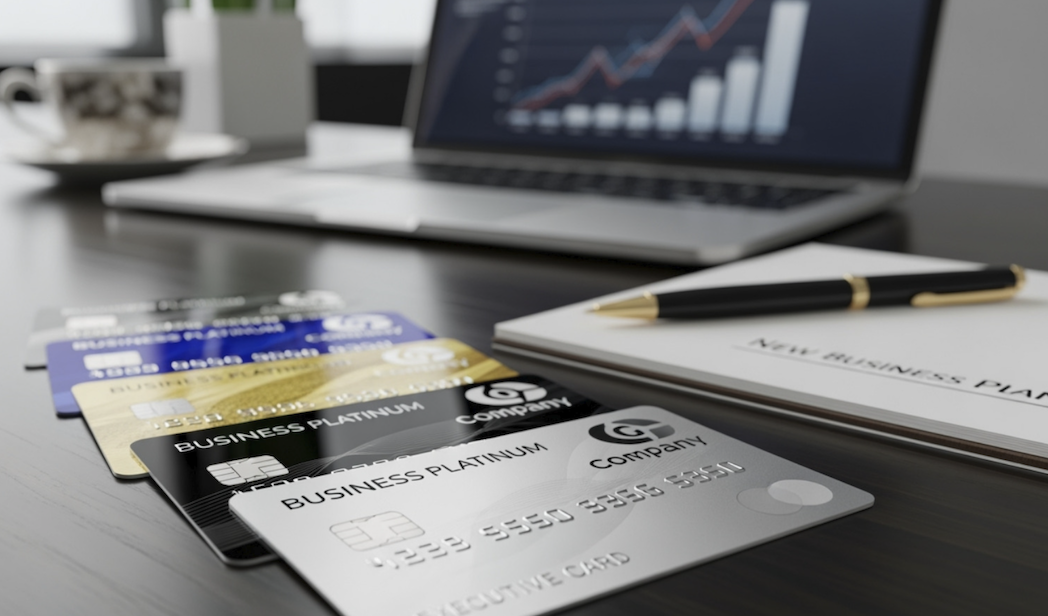
Business credit cards come in several distinct forms, each suited to a different spending pattern and credit profile, and picking the wrong type leads to either missed rewards or an account that does not fit how the business truly spends money.
- Standard business credit cards: Function similarly to a personal credit card, carrying a balance month to month with interest, suited to businesses that occasionally need short-term financing.
- Charge cards: Require the balance to be paid in full each month, which enforces financial discipline but removes the flexibility of carrying a balance during a slow period.
- Secured business credit cards: Require a cash deposit as collateral, useful for a newer business without an established credit history that would qualify for an unsecured card.
- Corporate cards: Typically issued to larger companies and often tied to the business’s own credit rather than the owner’s personal guarantee, with centralized expense controls for multiple employees.
Matching the card type to the business’s current stage, rather than chasing the most attractive rewards program regardless of fit, tends to produce a better long-term outcome.
Evaluating Rewards Programs and Fee Structures
Rewards programs can add real value over a year of business spending, but the right program depends entirely on where a business truly spends its money, and a card chosen purely for a flashy headline bonus often delivers less value than one matched to real spending patterns.
- Match reward categories to real spending: A card offering bonus rewards on advertising and software subscriptions benefits a marketing-heavy business far more than one offering bonus travel rewards it rarely uses.
- Calculate the real value of an annual fee: A card with a sizable annual fee can still be worth it if the rewards earned clearly exceed that cost, but this requires an honest calculation rather than an assumption.
- Check for foreign transaction fees: A business that pays international vendors or travels abroad regularly should prioritize a card that waives these fees entirely.
- Review redemption flexibility: Rewards that can only be redeemed for narrow, specific options are worth less in practice than cash back or flexible points that fit a wider range of business needs.
Running the numbers on realistic monthly spending across a few candidate cards, rather than comparing headline bonus offers alone, reveals which option delivers the most value for that specific business.
This exercise is worth repeating every year or two, since a card that made sense when the business was smaller or spending differently may no longer be the best fit once revenue grows or spending shifts into new categories. Many card issuers periodically revise their own reward structures as well, sometimes to a business’s benefit and sometimes not, so treating the current card as a permanent choice rather than a decision worth revisiting occasionally can leave real value unclaimed over several years of changed circumstances.
Issuing Employee Cards With Proper Controls
As a business grows beyond a single owner handling every purchase, employee cards become a practical necessity, but issuing them without proper controls creates both financial and oversight risk that can be avoided with a bit of upfront planning.
- Set individual spending limits per employee card: Limits matched to each role’s real needs prevent one employee’s card from becoming an unmonitored source of unchecked spending.
- Restrict card use to specific merchant categories when possible: Many providers allow blocking certain categories entirely, which prevents an employee card from being used somewhere clearly outside its intended purpose.
- Require receipts for every purchase above a set threshold: A simple policy requiring documentation keeps spending accountable without demanding a receipt for every minor purchase.
- Review all employee card statements monthly: Even with limits and category restrictions in place, a monthly review catches unusual patterns that automated controls alone might miss.
A clear written policy distributed to every employee who receives a card removes ambiguity about what counts as an appropriate business purchase, reducing both honest mistakes and the rare case of deliberate misuse.
Introducing this policy during onboarding, rather than handing someone a card with no guidance and assuming good judgment will fill the gap, sets expectations clearly from day one. A short document covering what categories of purchases are approved, how to submit receipts, and who to contact with questions turns what could be an awkward, ad hoc conversation into a standard part of starting a new role.
Revisiting the policy annually, adjusting limits or categories as the business’s needs change, keeps it a living reference rather than a document written once and forgotten in a folder nobody opens again after the first week.
Growing Business Credit Through Responsible Use
A business credit card does more than cover expenses; used consistently and responsibly, it builds a credit history for the business itself, separate from the owner’s personal credit, which matters increasingly as the business seeks larger financing down the road.
- Pay the full balance on time every month: Consistent, on-time payment is the single strongest factor in building a strong business credit profile over time.
- Keep utilization well below the credit limit: Using only a modest portion of the available credit limit each month signals financial stability to future lenders.
- Open the account with a reporting provider: Not every business card reports to the major business credit bureaus, so confirming this before applying matters for anyone building credit intentionally.
- Avoid closing old accounts unnecessarily: A longer credit history generally helps a business’s credit profile, so closing a well-managed older account can work against future financing goals.
A business with its own established credit history gains access to better financing terms and larger credit limits over time, reducing reliance on the owner’s personal credit for future growth.
This independence becomes especially valuable at moments when the business needs to raise capital, lease a larger space, or finance a major equipment purchase, since lenders and landlords increasingly look at a business’s own credit profile rather than treating every application as a reflection of the owner’s personal finances alone.
A business that neglected this groundwork in its early years often finds itself at a disadvantage during exactly these pivotal moments, needing to lean more heavily on a personal guarantee than a more established competitor with years of clean business credit history already behind it.
Reconciling Statements Each Month
A business credit card only delivers its organizational benefit if the statements that come with it get reviewed and reconciled against the company’s books on a truly regular basis. Letting statements pile up unread defeats much of the purpose of having a dedicated card in the first place, since errors, duplicate charges, or unauthorized use can go unnoticed for months.
A short, well-structured monthly routine keeps this task from ever becoming a real burden on anyone’s time. Setting aside a fixed time each month, right when the statement arrives, to compare every line item against receipts and expected purchases catches discrepancies while they are still fresh and easy to resolve with a vendor. Categorizing each charge as it is reviewed, rather than leaving that work for tax season, keeps the business’s financial picture current and ready for decision-making at any point in the year rather than only once annually.
Most card issuers also offer an exportable transaction file compatible with common bookkeeping software, which removes much of the manual data entry that used to make this process tedious.
Disputing an incorrect or fraudulent charge becomes far easier when it is caught within the statement cycle it appeared on, since most card issuers have a limited window for formal disputes. A business that reviews its statement promptly each month protects itself far better against this kind of loss than one that only glances briefly at the total due before paying it off.
Transitioning From a Personal Card to a Business Card
Many business owners start out using a personal card simply because that is what was available when the business first needed to make a purchase, and transitioning away from that habit later requires a bit of deliberate effort rather than happening automatically on its own.
The cleanest approach involves a clear cutoff date after which every business purchase goes exclusively on the new business card, with no exceptions made for convenience. Existing recurring charges, such as software subscriptions or utility payments tied to the business, need to be updated individually with the new card details, which can take a few weeks to fully migrate across every vendor and service involved.
Keeping the old personal card accessible for a short overlap period, strictly for catching anything missed during the transition, smooths out this process nicely without creating a hard gap in coverage anywhere along the way.
Once the transition is complete, maintaining the discipline to never slip back into using a personal card for a quick, convenient purchase protects the clean separation that took effort to establish. A single lapse rarely causes serious harm, but a habit of occasional exceptions slowly erodes the very separation the whole effort was meant to create, so treating the business card as the only acceptable option for company spending from that point forward is well worth the small inconvenience it occasionally creates.
Final Thoughts
A dedicated business credit card is one of the simplest structural changes a small business owner can make to protect personal assets, simplify tax preparation, and build a credit profile separate from personal finances.
Choosing the right card type, matching rewards to real spending patterns, and setting clear controls for any employee cards turn what could be a source of confusion into a tool that actively supports the business’s financial health.
The earlier this separation happens, the less untangling there is to do later, and the more straightforward every tax season and financing conversation becomes as the business continues to grow in the years ahead.
Frequently Asked Questions
1. Does a business need to be incorporated to get a business credit card?
No, sole proprietors and freelancers can typically apply for a business credit card using their own Social Security number in place of a separate business tax identification number altogether. Many card issuers accept any legitimate, income-generating business activity, even one still operating under the owner’s own name rather than a formally registered business entity of any kind.
2. Will a business credit card application affect personal credit?
Most business credit cards still require a personal guarantee from the owner, especially for a newer or smaller business, which generally means a personal credit check happens somewhere during the application process. Some larger, more established businesses can eventually qualify for cards that rely primarily on business credit rather than a personal guarantee, which reduces this direct connection to the owner’s personal credit standing over time as the business matures.
3. How many business credit cards should a company have?
There is no universal answer, but many small businesses operate well with just one primary card for the owner and a small number of employee cards issued only to those who need to make regular purchases on behalf of the company. Adding more cards than necessary increases the complexity of tracking spending and reconciling statements each month without a proportional benefit to the business overall, so it is worth staying deliberate about who truly needs one.
4. Can a business credit card help during a slow revenue period?
A business card with a reasonable credit limit can provide a short-term cushion during a temporary cash flow gap, but relying on revolving credit as a long-term solution to ongoing revenue problems is risky given the interest costs involved. It works best as an occasional buffer during an unusually tight month rather than a routine, ongoing source of operating capital for the business as a whole.
5. What should a business do if an employee misuses a company card?
Most providers allow an account holder to immediately freeze or cancel an individual employee card without affecting other cards tied to the same account, and this step should happen as soon as misuse is identified, without waiting for a full investigation to conclude first. Following up with a clear, direct conversation, and in serious cases a formal written record of the incident, protects the business well if the situation ever needs to be addressed through further action later on.
6. Are rewards earned on a business credit card taxable?
Generally, rewards earned from business spending are treated as a rebate or discount on the original purchase rather than taxable income, which closely mirrors how personal credit card rewards are typically treated as well under most common tax guidance. Specific tax treatment can vary somewhat by situation and by jurisdiction, so a business earning substantial rewards is wise to confirm the current rules with a tax professional rather than assuming a single blanket answer applies in every single case.