How to Build a Holiday Budget That Stops Overspending in November and December
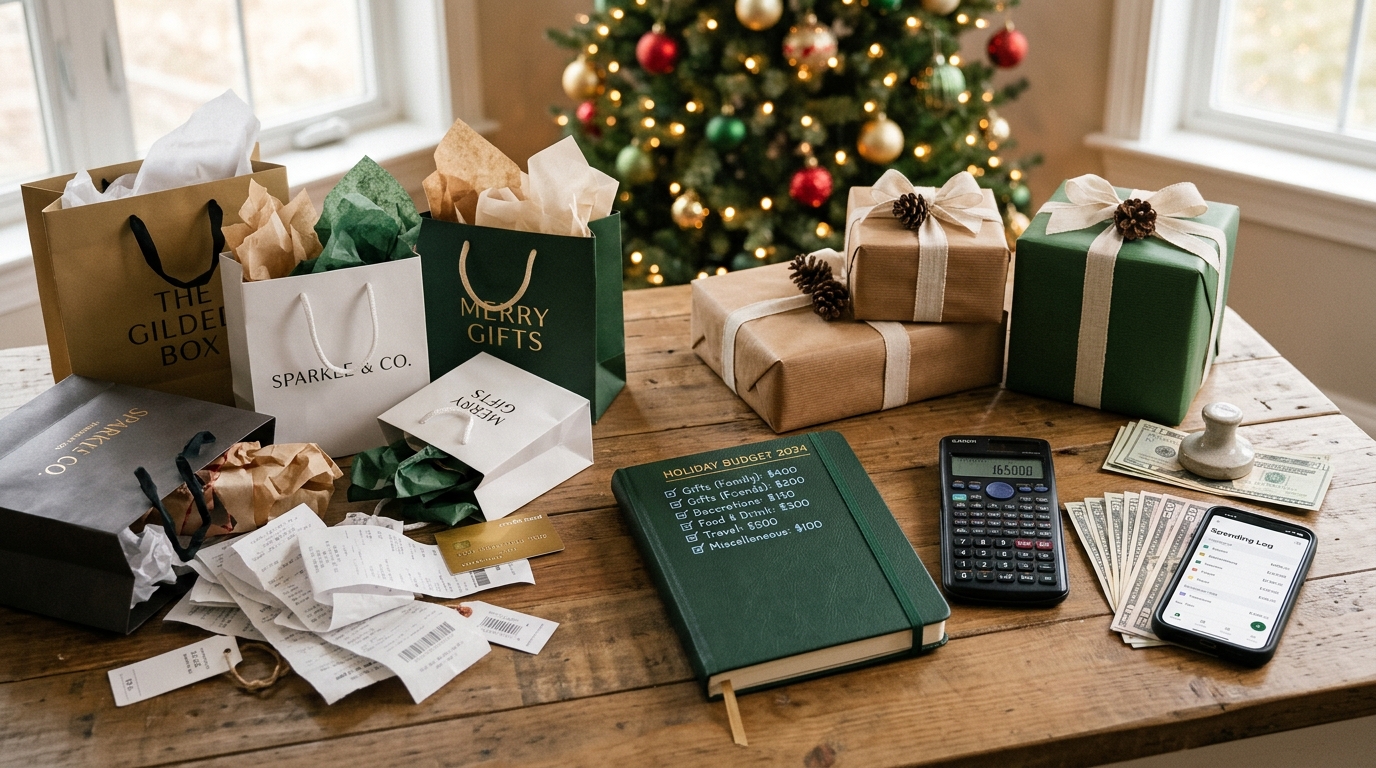
Holiday celebrations can put a hefty strain on your budget. Between Thanksgiving celebrations, Christmas gifts, travel expenses, family gatherings, decorations, and New Year’s Eve plans, spending can quickly get out of control. Even people who manage their money carefully throughout the year may find themselves struggling financially by January.
Overspending isn’t always caused by having too little money. Often, it comes from shopping without a clear plan, underestimating small expenses, and making emotional purchases during holiday sales.
Building a holiday budget before November begins can help you enjoy the celebrations without putting unnecessary pressure on your finances. With a realistic spending limit, a little preparation, and consistent tracking, you can avoid overspending and start the new year in a stronger financial position.
Why Holiday Spending Gets Out of Control
Holiday expenses often increase because people focus on individual purchases instead of their total spending.
For example, spending $30 on a gift might not seem like a problem. However, purchasing gifts for ten people already adds up to $300. Add decorations, food, travel, and entertainment, and the total can become much higher than expected.
Several common habits contribute to holiday overspending.
Emotional Shopping
People sometimes purchase expensive gifts because they want to make family members happy or feel pressure to match what others are buying.
Retailers also use limited-time offers and holiday promotions to encourage quick purchasing decisions.
Ignoring Small Expenses
Coffee, gift wrapping, holiday snacks, shipping fees, and small decorations may seem inexpensive individually. However, these purchases can consume a significant portion of your budget when combined.
Using Credit Cards Without a Repayment Plan
Credit cards make it easier to spend money without immediately feeling the financial impact. Unfortunately, unpaid balances can accumulate interest and become a problem after the holidays.
Recognizing where and why you spend is a good starting point for building a practical budget.
Step 1: Calculate How Much Money You Can Afford to Spend
Before buying anything, determine how much money you can realistically dedicate to the holiday season.
Start by reviewing your monthly income and essential expenses, including:
- Rent or mortgage payments
- Utility bills
- Groceries
- Transportation
- Insurance
- Loan payments
- Existing savings commitments
After covering these responsibilities, calculate how much money remains.
For example, imagine your monthly take-home income is $3,500. Your essential expenses and regular financial commitments total $2,800. You have $700 remaining, but you should not automatically spend all of it on holiday activities.
You might decide to allocate $300 toward holiday expenses and keep the remaining $400 for savings, emergencies, or other financial priorities.
The goal is to establish a spending limit that does not interfere with your normal financial responsibilities.
Step 2: Create Separate Categories for Holiday Expenses
A single holiday spending limit is helpful, but dividing it into categories makes your budget easier to manage.
Consider creating separate categories for the following expenses:
Gifts
List everyone you plan to purchase gifts for and establish a spending limit for each person.
Your gifts don’t have to cost the same for every person on your list. Prioritize your closest relationships and choose affordable gifts for other occasions.
Food and Celebrations
Include groceries, restaurant visits, holiday dinners, drinks, desserts, and family gatherings.
Remember that hosting a celebration can cost more than expected, especially when you purchase everything at the last minute.
Travel and Transportation
If you plan to visit family or friends, include fuel, flights, accommodation, parking, public transportation, and other travel-related expenses.
Decorations and Entertainment
Set aside money for holiday decorations, seasonal activities, movies, events, and other entertainment.
Unexpected Expenses
Keep a small amount available for unexpected costs, such as additional guests, last-minute invitations, or forgotten purchases.
Separating expenses helps you understand where your money is going and prevents one category from consuming your entire budget.
Step 3: Start Saving Before November
One of the easiest ways to avoid holiday financial pressure is to start saving before the expensive season arrives.
Instead of paying for everything in November and December, gradually set aside money throughout the year.
For example, if your holiday spending target is $600, saving $50 every month for 12 months will give you the full amount before the holiday season.
If you are starting later, calculate how much you need to save from your remaining paychecks.
You can also create a separate savings account or use a dedicated savings category in your budgeting app. Keeping holiday money separate from everyday spending makes it easier to avoid accidentally using it.
The important thing is to save an amount that fits your financial situation rather than forcing yourself to meet an unrealistic target.
Step 4: Plan Your Shopping List Before the Holiday Deals Start
Holiday discounts can make unnecessary purchases feel like smart financial decisions.
However, a discounted product is not automatically a good deal if you were never planning to purchase it.
Before November sales begin, create a shopping list that includes everything you genuinely need.
For each purchase, write down:
- The item you want to buy
- The person receiving the gift
- Your maximum spending limit
- The expected purchase date
- Whether the purchase is essential or optional
Compare prices between different retailers before making a decision.
You should also avoid browsing shopping websites simply because they advertise seasonal discounts. Shopping without a specific purpose increases the chances of impulse buying.
A prepared shopping list keeps your attention on planned purchases instead of attractive promotions.
Step 5: Set a Spending Limit for Every Gift
Gift shopping is one of the biggest sources of holiday overspending.
People often feel uncomfortable spending less on someone they care about. However, meaningful gifts do not always require expensive purchases.
Start by creating a list of recipients and assigning a maximum amount to each gift.
For example:
| Recipient | Spending Limit |
| Parents | $100 |
| Partner | $80 |
| Siblings | $60 |
| Friends | $40 |
| Colleagues | $20 |
| Total | $300 |
These figures are only examples. Adjust them according to your income and overall holiday budget.
You can also consider affordable alternatives, such as handmade gifts, personalized photo albums, homemade food, or shared experiences.
If your family has several members exchanging gifts, suggest a gift exchange where everyone purchases for one person instead of buying something for the entire group.
This approach can reduce expenses without removing the enjoyment of giving.
Step 6: Use Cash or Separate Spending Accounts
One practical way to control holiday expenses is to separate your spending money from your regular finances.
You can use cash envelopes, a prepaid card, or a separate checking account.
For example, if your holiday gift budget is $300, transfer that amount into your designated spending account. Once the money is gone, avoid making additional purchases unless you adjust another category.
This method creates a clear financial boundary.
Credit cards can also be useful when you pay the full balance on time and understand the terms. However, avoid treating your credit limit as additional holiday income.
If you cannot comfortably repay a purchase, consider choosing a less expensive alternative.
Step 7: Track Every Purchase During November and December
Creating a budget is only the beginning. You also need to monitor your spending throughout the holiday season.
A simple spreadsheet, notebook, or budgeting application can help you record purchases.
Your tracker should include the purchase date, item, category, amount, and remaining budget.
For example, if you allocate $300 for gifts and spend $85 during the first week of November, you should know that $215 remains.
Check your spending at least once a week.
Regular reviews help you identify problems early. If you spend too much on decorations, you can reduce entertainment expenses rather than allowing your overall budget to increase.
Tracking also makes it easier to recognize unnecessary purchases and improve your financial habits for the following year.
Step 8: Avoid Last-Minute Shopping
Last-minute shopping often leads to higher expenses because people have fewer opportunities to compare prices.
Popular products may become unavailable, delivery costs can increase, and shoppers may purchase more expensive alternatives simply because they are in a hurry.
Start buying gifts and necessary supplies early whenever possible.
However, early shopping should not become an excuse to purchase unnecessary items. Stick to your original list and avoid buying things simply because they are available at a discount.
Preparing in advance can help you shop more thoughtfully and keep your spending in check.
Step 9: Find Affordable Ways to Enjoy the Holidays
Enjoying the holiday season does not require expensive celebrations.
There are several ways to reduce costs while still creating meaningful experiences.
Consider these ideas:
- Organize a potluck dinner where everyone brings one dish.
- Watch holiday movies at home instead of purchasing expensive event tickets.
- Use existing decorations rather than buying new ones every year.
- Choose local activities that offer free admission.
- Share transportation costs when visiting family.
- Make personalized gifts instead of purchasing expensive products.
- Set a reasonable restaurant spending limit before going out.
Small adjustments can reduce holiday expenses without making celebrations feel less special.
Step 10: Prepare for January Before December Ends
Many people focus so much on November and December that they forget about January expenses.
However, regular bills, rent, loan payments, insurance, and other financial responsibilities continue after the holidays.
Before spending your remaining holiday budget, make sure your January obligations are covered.
Avoid using money reserved for essential bills to purchase additional gifts or attend extra celebrations.
If you have leftover holiday savings, consider moving that money into an emergency fund or starting a savings category for the next holiday season.
Preparing for January helps prevent holiday spending from becoming a financial problem that continues into the new year.
Common Holiday Budgeting Mistakes to Avoid
Even a carefully planned budget can fail when you overlook certain habits.
Here are some mistakes worth avoiding:
Ignoring delivery and additional fees: Shipping, taxes, parking, and service charges can increase the final cost of purchases.
Buying gifts out of guilt: You should not feel obligated to spend more than you can afford to make someone happy.
Treating every sale as an opportunity: Discounts only save money when they apply to something you actually need.
Borrowing for unnecessary celebrations: Taking on debt for expensive gifts or entertainment can create financial stress long after the holidays.
Failing to review your budget: Without regular tracking, it becomes difficult to recognize overspending before it happens.
Avoiding these mistakes can make your holiday budget more realistic and easier to maintain.
Final Thoughts
Building a holiday budget that stops overspending in November and December does not mean avoiding celebrations or refusing to purchase gifts. It means making thoughtful financial decisions before the holiday season becomes busy.
Start by calculating your available spending money, dividing expenses into categories, setting gift limits, and tracking every purchase. Avoid unnecessary credit card debt, take advantage of planned shopping opportunities, and protect the money you need for January.
Most importantly, remember that the value of the holiday season comes from spending time with people you care about, not from how much money you spend.
With a realistic plan and consistent spending habits, you can enjoy November and December celebrations while keeping your finances under control.